Independent monitoring of systemic procedural violations
When an official hearing duration and the available audio record do not align, the question is not what we would like the numbers to mean. It is what the underlying documents establish—and what remains to be explained.
| HEARING DURATION | AVAILABLE AUDIO |
|---|---|
| 150 min | ~77 min |
| DIFFERENCE REQUIRING RECONCILIATION | |
| 73 minutes | |
The comparison uses the approximately 77-minute duration adopted in this audit. It identifies a discrepancy between the recorded hearing duration and the audio material available for examination; it does not, by itself, establish the reason for that difference.
The judgment records the hearing duration as two and a half hours. The two audio files made available for this audit contain approximately 77 minutes of material.
These are two distinct documentary facts. The first concerns the duration stated in the judicial record. The second concerns the duration of the audio material available for review.
Their difference is substantial enough to warrant a clear explanation. The comparison does not establish that every minute of a hearing must consist of continuous recorded speech. It does establish that the two records, as presently available, do not account for the same duration.
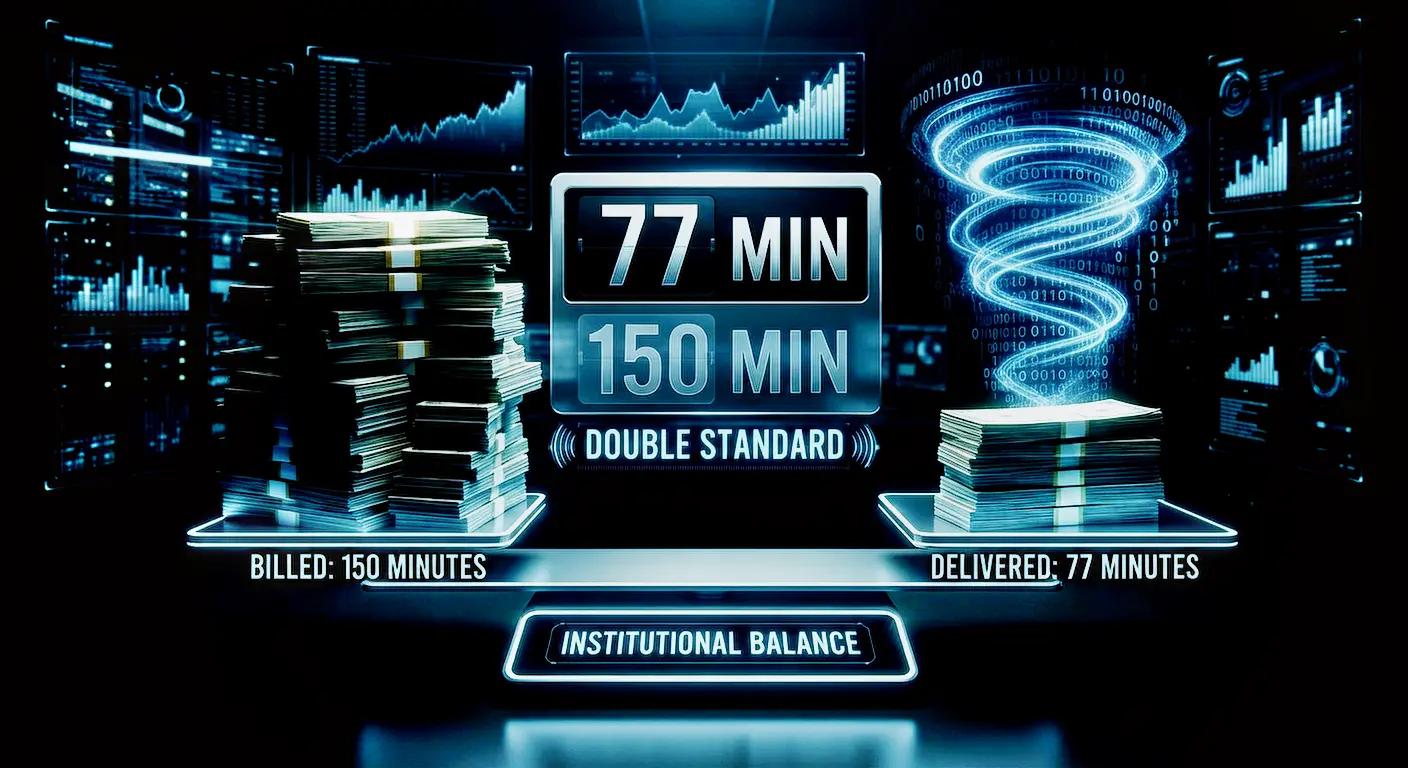
The central question is precise: what accounts for the difference between the recorded hearing duration and the duration of the supplied audio material?
Several explanations are conceivable in principle: additional recordings may exist; the stated duration may include intervals not represented in the supplied files; or the official duration may have been calculated according to a different procedural measure.
These are possibilities to be tested against documents, not findings about what happened in this case.
The distinction matters. Suggesting a possible explanation does not reconcile the records. Reconciliation requires identifying the relevant material, procedural interval, or applicable calculation method.
A useful audit therefore separates three things:
Until the third element is identified, the discrepancy remains unresolved in the materials examined here.
The duration question also has a financial dimension. In this case, the legal service was billed on the basis of a two-and-a-half-hour hearing at €200 per hour: €500 before VAT.
The financial record and the audio record serve different purposes. The invoice establishes the amount charged for the stated period. The audio files establish the duration of the material supplied for examination. Neither should be silently substituted for the other.
| Recorded hearing duration | 2.5 hours |
| Hourly rate | €200 |
| Amount before VAT | €500 |
A separate arithmetic calculation values 73 minutes at €200 per hour at approximately €243.33. That is a hypothetical rate-based comparison—not proof that this amount was improperly charged, separately invoiced, or owed as a refund.
The practical issue is whether the duration used for billing can be understood from the relevant records and the basis on which the time was charged.
Digital audio can be examined through measurable properties, including duration, file size, metadata, timestamps, and the presence of separate segments. Those properties can help establish what material is available and whether the supplied files contain gaps or interruptions.
Such examination has limits. File duration alone cannot establish what occurred outside a recording, whether another recording exists, or what a particular financial entry was intended to cover.
Its value lies in making the comparison reproducible. Another reviewer can examine the same files, verify their duration, and compare that result with the official documentation.
A measurable discrepancy is a legitimate subject of documentary scrutiny even before its cause has been established.
The comparison gives rise to a limited set of questions that can be answered through records:
These questions do not presume fraud or technical failure. They identify what would be needed to explain the discrepancy and allow independent scrutiny of the answer.
The comparison in Case R 706/2025/5226 places three matters side by side: a hearing duration of 150 minutes in the judicial record, approximately 77 minutes of available audio material, and a legal-service charge of €500 before VAT for two and a half hours.
These records do not answer the same question. Their relationship must be established through the relevant documentation rather than assumption.
The discrepancy should neither be dismissed without explanation nor automatically treated as proof of wrongdoing. Its significance lies in the fact that it can be checked, documented, and put to a precise question.
Official time, recorded material, and financial charges should be capable of being understood together. Where they do not align, the records should explain why.
See also: Technical Evidence Audit: Discrepancies in Court Documentation
Related materials should be linked to the verified lawbeatradio.com address.
Independent legal media platform focusing on structural judicial monitoring and criminal case analysis. We examine international standards of justice, from the presumption of innocence to the rigorous evaluation of the standard of proof and in dubio pro reo principles.
All analytical materials and legal case reviews on this website are published for informational and educational purposes only under freedom of expression. Content does not constitute professional legal advice.
© 2026 LawBeatRadio. All rights reserved.